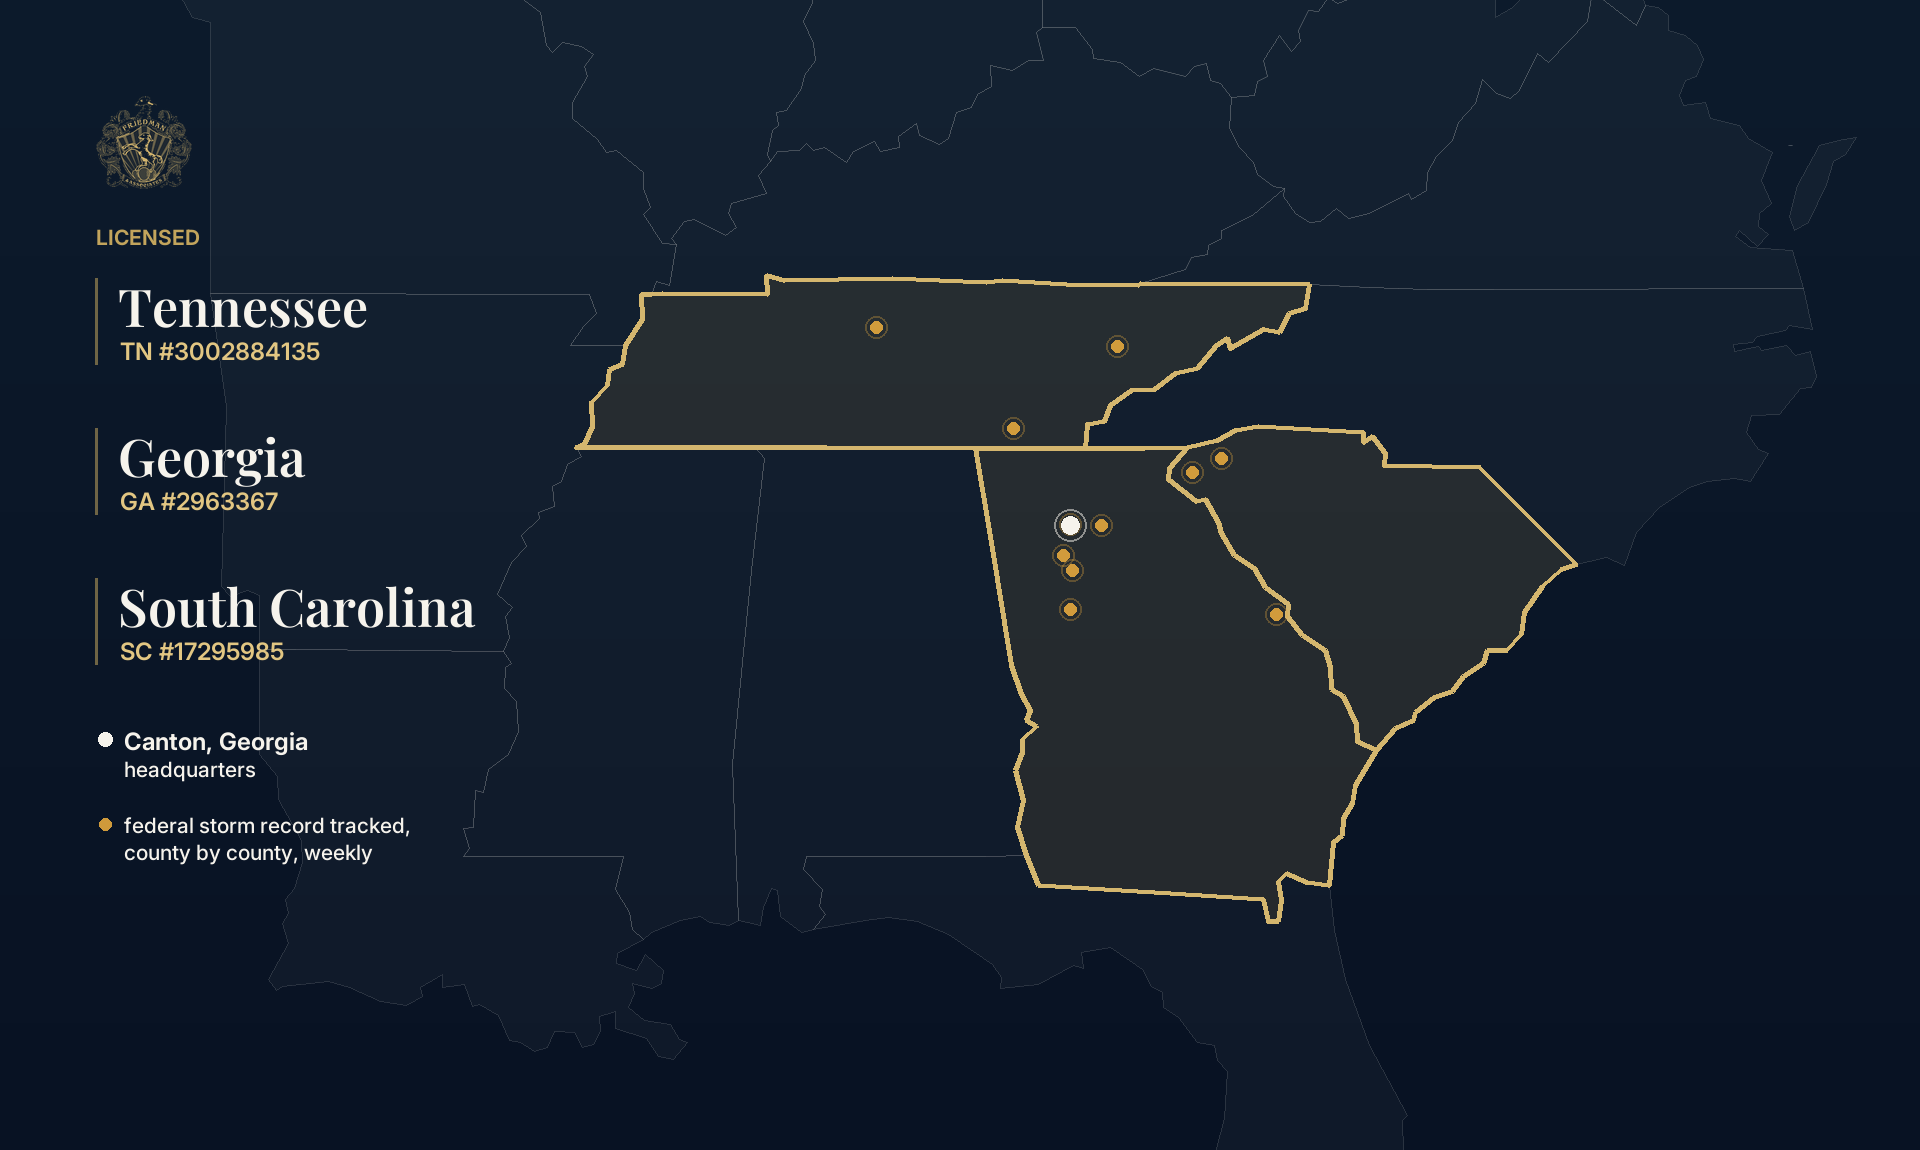
The short answer: For fine homes, estates, and complex high-value losses, Friedman & Associates runs a dedicated private-client practice: strict confidentiality, your file held at the partner level, and the expert bench your policy deserves. Underpaid and denied high-value claims are our specialty. Licensed in Georgia, Tennessee, and South Carolina. No recovery, no fee. Call 877-650-3515 or text the partners.
Call us before you call your carrier. The first phone call shapes the whole claim. Already filed, or an adjuster already assigned? We're still your next call.
Prefer a private conversation first? Call 877-650-3515 and skip the form entirely. We'll sign your NDA before we read a single document.
What we take command of
Results and press
$1,664,329 recovered above the carriers' first offers on just 10 recent published files, from more than a decade of this work. See real case results. You could be next.
"He helped me recover 4 times what insurance was offering… extremely diligent and moralistic in how he worked."Kelly, Google review · 4.8★ across 23 reviews · read them all
When you hire the firm, you get the partners: Joshua and Hannah Friedman, with Callie Macho on client success. Not a call center.
Want the fuller picture first? The film, the results register, and the client portal are all at the front door. Meet the firm →
Why custom construction loses on the carrier's price sheet
Carrier estimates come out of software that prices standard grades: architectural shingle, builder trim, stock glass. Custom construction, collections, and unique endorsements are exactly where standard-grade estimates fail. The policy's own standard is like kind and quality, and finding the overlooked detail that changes the outcome is the practice.
Discretion is the default. Your information stays secured, your claim is discussed with no one outside the file, and the people reading it are the partners, not a case queue. Fine art, wine, and the endorsements that schedule them run in their own valuation lane, appraised by specialists rather than priced from a spreadsheet. And we do not publish private-client case studies, by design.
Private-client handling is not about the size of the house. It is about the size of what is at stake. A $150,000 home with asbestos in the ceilings can become a total loss the day the first wall opens: code upgrades and abatement push repairs past what the house is worth, and the carrier will not be the one to tell you. That file needs the same bench as any estate, and here it gets it. The fee comes from the recovery, so this door has no minimum.
Not every claim qualifies. Three taps to find out if yours does.
The law and the clock
A high-value claim may involve policy deadlines, valuation disputes, and legal remedies that require separate analysis. If the policy contains an applicable appraisal clause and the disputed questions fall within what it assigns to a panel, either party may demand appraisal under that clause. The exact policy and claim record control. The full discussion sits on our shelf, free: why a high-value claim demands a specialist.
One clock outranks everything: your policy's own "Suit Against Us" clause. Read it the day a claim goes sideways. Do not assume negotiations extend the deadline; the governing policy and law control, and deadline questions belong with counsel.
Questions owners ask
Who sees our file?
The partners, and no one else. Your claim is discussed with no one outside the file, and every document lives in a secure client portal that only you and we can open.
Should I call you before I call my insurance company?
Yes. What gets said in the first call shapes the whole claim, so talk to us first. Already filed, or an adjuster already assigned? Call us anyway. We step in at any stage, and the earlier the better.
Do you work with our family office or attorney?
Yes, and often. We report to your family office on its terms and work beside your counsel. The carrier fight is ours to carry.
Can you handle art, wine, and collections?
Yes, with the right bench. Collections run in their own valuation lane, appraised by specialists and documented item by item against the endorsement that schedules them.
Our policy "guarantees" full replacement. Doesn't that settle it?
Only as far as the written words reach. Guaranteed and extended replacement endorsements carry their own definitions, caps, and conditions, so we read the exact language before accepting the carrier's version of it.
Our builder offered to handle the insurance claim. Is that normal?
It is common, and the roles are best kept clean. That is no knock on your builder. We handle the carrier, your builder handles the build, and we work well beside good contractors.
What does private-client handling cost?
Nothing up front. The fee is a contingency paid out of what we recover, agreed in writing before we start. If we recover nothing, you owe nothing.
Prefer a quieter first step? Ask us anything, free: a real answer from a licensed adjuster, no strings.
Friedman & Associates are licensed public adjusters in Georgia, Tennessee, and South Carolina, not attorneys. Our work is the licensed practice of public adjusting: reading the policy, documenting and valuing the loss, negotiating with the carrier, and preparing appraisal. Nothing on this page is legal advice, and litigation, including bad-faith suits, is referred to independent policyholder counsel.

High-value claims deserve partner-level handling. A confidential conversation with the partners, directly. If we take the case, the fee comes from the recovery, never from you.
See if my case qualifies 877-650-3515